China CSSC Holdings Ltd. Secures a 172 Billion‑CNY VLCC Order
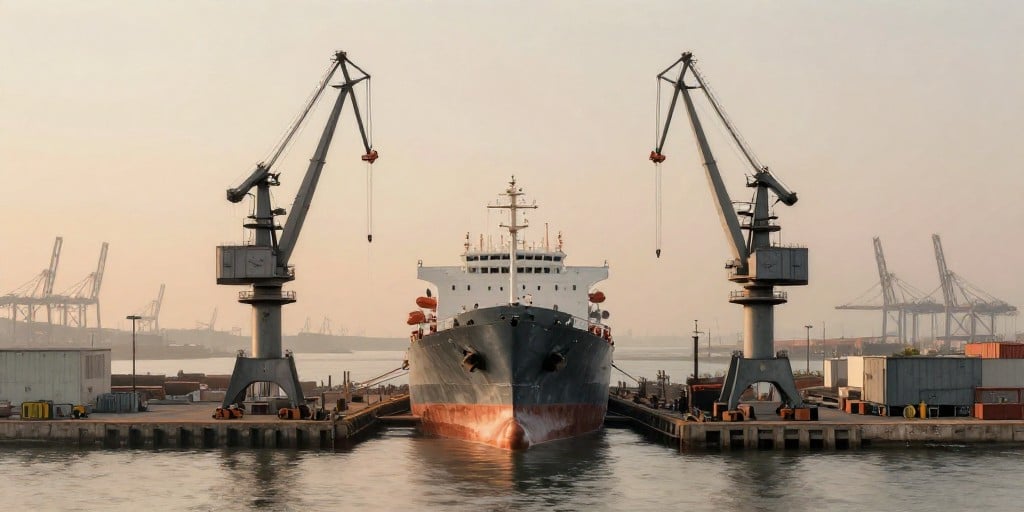
China CSSC Holdings Ltd. (SH600150) announced that its wholly‑owned subsidiary, Dalian Shipbuilding Co. Ltd. (DSC), has signed a comprehensive contract to build 20 ultra‑large crude carriers (VLCCs) for two of China’s major shipping groups. The project, valued at approximately 172 billion CNY (US$26.5 billion), includes 30.7‑thousand‑tonne vessels that will be delivered beginning in 2029.
Contract Highlights
| Party | Number of Ships | Unit Size | Contract Value | Currency |
|---|---|---|---|---|
| Hainan Hai‑Neng (sub‑company of COSCO Shipping Energy) | 4 | 30.7 kt | 37.93 billion CNY | RMB |
| Dongfang Fuli (sub‑company of COSCO Shipping Holdings) | 1 | 30.7 kt | 5.00 billion CNY | RMB |
| Remaining 15 Ships | 15 | 30.7 kt | 129.25 billion CNY | Cross‑border RMB |
The agreement covers both domestic and cross‑border RMB payments, ensuring a stable cash‑flow profile for CSSC’s capital‑intensive build‑to‑order operations.
Market Context
- VLCC demand has rebounded after a period of oversupply during the pandemic, driven by lower crude prices and increased global shipping needs. Analysts expect the segment to grow steadily through the early 2030s as global trade expands and crude inventories normalize.
- CSSC’s position in the Chinese shipbuilding sector remains unchallenged. The company’s diversified product range—ship construction, ship‑components, repair services, and diesel‑engine manufacture—provides resilience against sectoral shocks.
- Financials: As of 2026‑11‑11, CSSC traded at 34.2 CNY, 16.21 × P/E, and a market capitalization of 35.3 billion CNY. The recent order aligns with the company’s long‑term growth strategy, potentially boosting EBIT margins by 2–3 percentage points over the next five years.
Strategic Implications
Revenue Acceleration The 172 billion‑CNY contract translates to an estimated 20‑year revenue stream of roughly 8.6 billion CNY per year, assuming a linear delivery schedule. This will significantly lift the company’s top line and improve profitability once the capital costs are amortized.
Capacity Utilisation CSSC’s three major shipyards—Dalian, Yantai, and Zhanjiang—will see heightened utilisation rates. The 30.7‑kt VLCCs require advanced welding, modular construction, and stringent quality control, reinforcing CSSC’s reputation for engineering excellence.
Supply‑Chain Strengthening The order consolidates relationships with key suppliers of steel, propulsion systems, and automation equipment. The recent inclusion of new automation partners (e.g., Xinshao Robot’s membership in the China Shipbuilding Industry Association) suggests that CSSC is poised to integrate cutting‑edge robotics into its production lines, potentially reducing build times and labor costs.
Risk Mitigation With a mixed payment structure (domestic and cross‑border RMB), the firm hedges against currency volatility and mitigates financing risk. Additionally, the long delivery horizon spreads capital expenditures over several fiscal periods, smoothing out cash‑flow volatility.
Forward Outlook
Stock Performance CSSC’s share price has retraced roughly 20 % from its year‑high following the announcement, reflecting market caution amid broader macroeconomic uncertainties (e.g., central bank monetary policy tightening and commodity price swings). However, the fundamental upside from the VLCC order should offset short‑term volatility, positioning the stock for a rebound as project execution progresses.
Sector Dynamics The global shift toward low‑carbon shipping and the anticipated rise in LNG‑powered vessels may create new opportunities for CSSC’s diesel‑engine division. Meanwhile, the company’s ability to deliver large‑scale projects positions it favorably against competitors in both China and Southeast Asia.
Regulatory Environment The Chinese government’s emphasis on sustaining domestic shipbuilding capacity and the recent issuance of a 7‑year fixed‑rate bond to finance infrastructure projects provide a supportive backdrop for CSSC’s growth plans.
Conclusion
China CSSC Holdings Ltd.’s 172 billion‑CNY VLCC order represents a decisive win in an industry recovering from pandemic‑induced disruptions. The deal not only delivers substantial revenue but also reinforces CSSC’s leadership in large‑scale ship construction, its integration of advanced manufacturing technologies, and its strategic positioning within China’s maritime logistics ecosystem. Investors should view this contract as a catalyst for medium‑term earnings growth, while remaining vigilant to the broader macroeconomic and commodity‑price headwinds that continue to shape the industrial sector.